Tips
How to File a Roof Insurance Claim in Illinois: A Step-by-Step Guide
November 1, 2026
Culture Construction Team·4 min
<p>A hailstorm rolls through on a Tuesday night. By Wednesday morning you're standing in your driveway looking at dented gutters and shingle granules piled against your downspout. You have homeowner's insurance. You know the storm did damage. But you have no idea what happens next — and the wrong first move can cost you thousands.</p>
<p>Here's exactly what to do, in order.</p>
<h2>Step 1: Document Everything Before Anyone Touches the Roof</h2>
<p>Before you call your insurance company — before you call a contractor — walk your property and photograph everything you can safely see from the ground. Get the gutters, the siding, any damaged windows, and whatever is visible at the roof edge. Date-stamped photos matter. If you have a security camera or doorbell cam that captured the storm, save that footage now.</p>
<p>If a neighbor's roof was also hit, note that. Insurance adjusters respond to neighborhood-wide damage differently than they respond to isolated claims. It's context that helps your case.</p>
<h2>Step 2: Call a Contractor Before the Adjuster Comes Out</h2>
<p>Most homeowners do this backwards. They call the insurance company first, wait for an adjuster, and then bring in a contractor to react to whatever the adjuster found.</p>
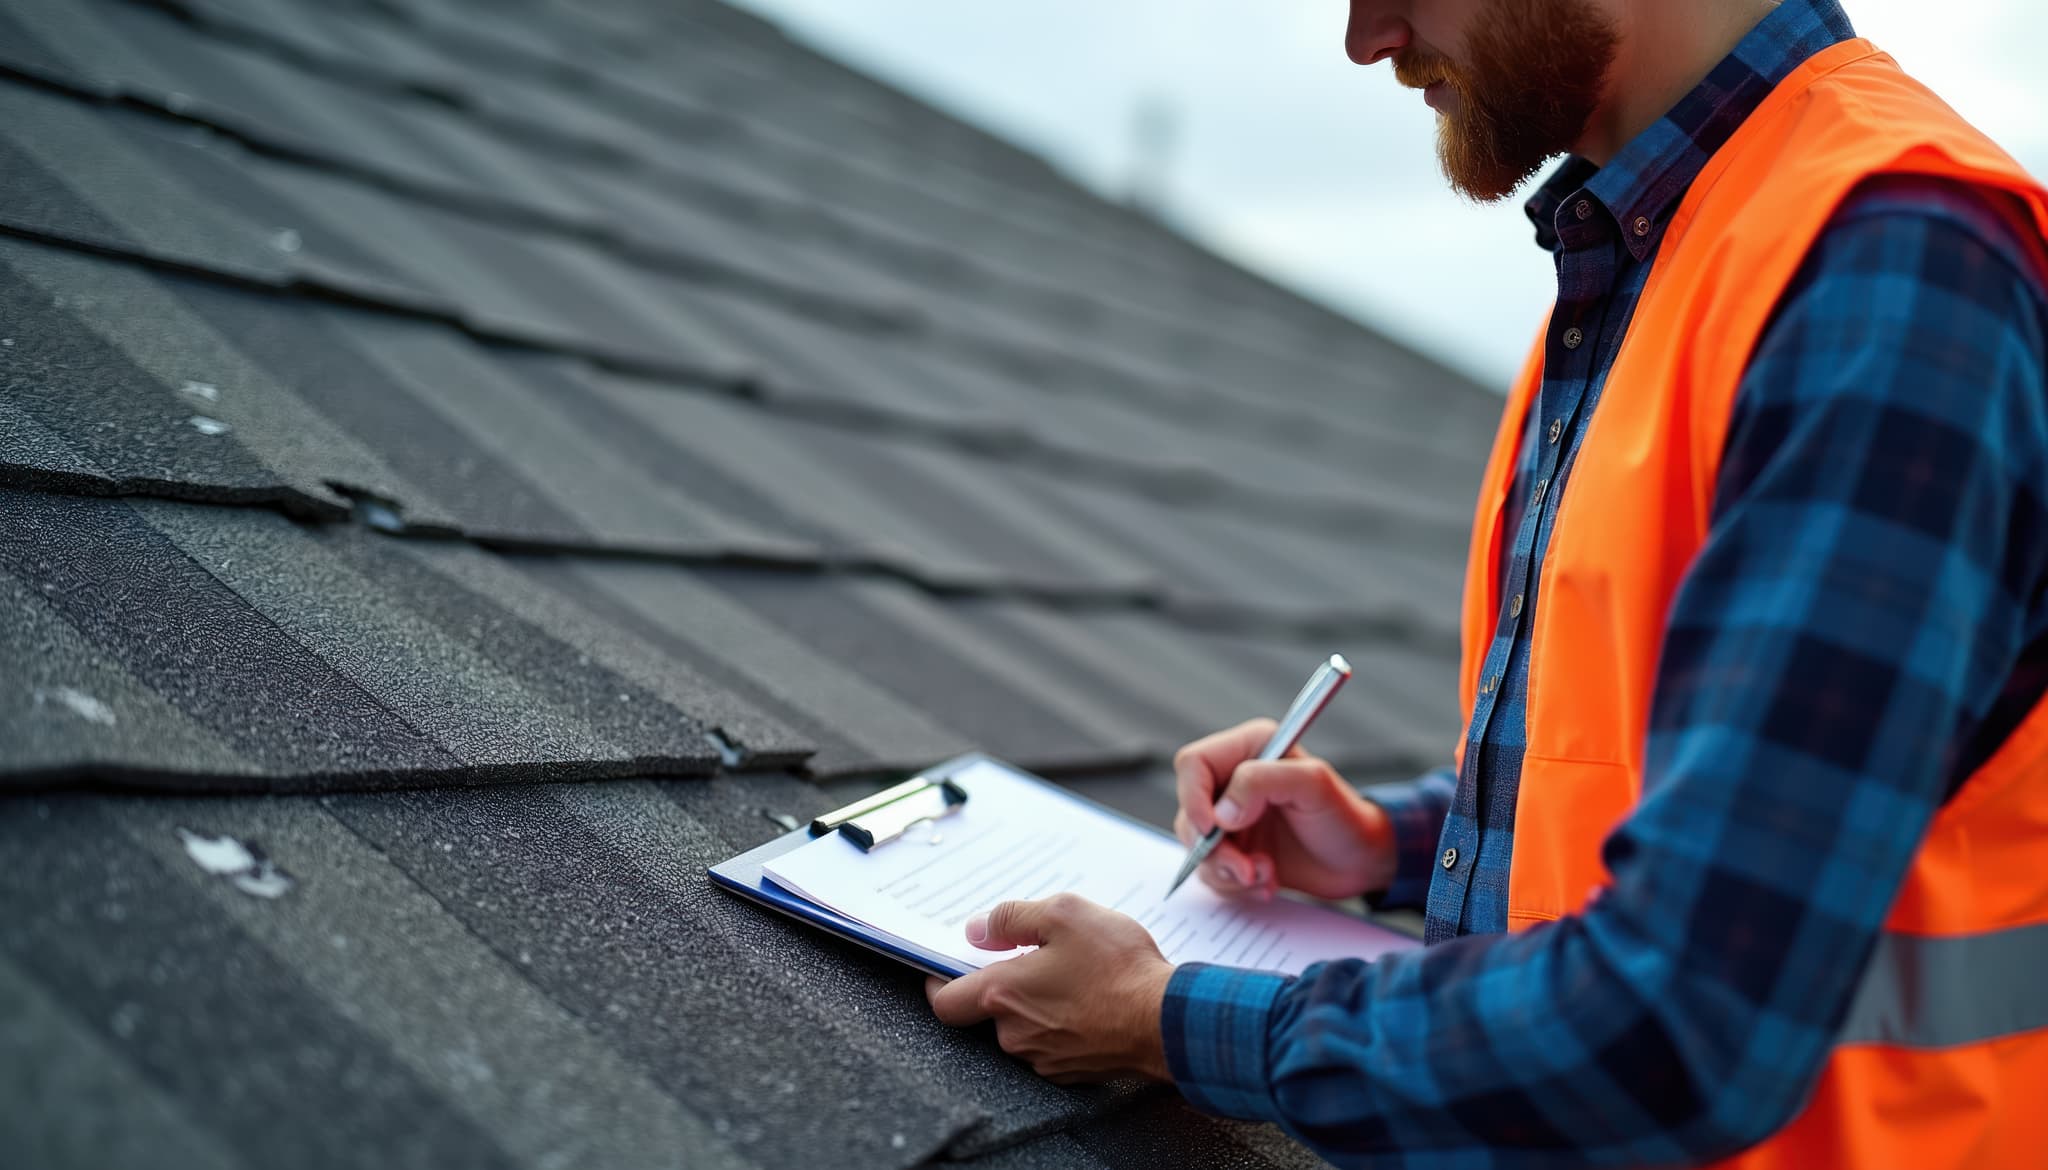
<p>Do it the other way around. A contractor who knows storm damage — specifically hail, wind, and ice damage in the Chicagoland climate — will inspect the roof with you, document everything in detail, and be present when the adjuster arrives. An experienced contractor can identify damage the adjuster misses and make sure it gets included in the scope of the claim.</p>
<p>That's not fighting the insurance company. That's making sure the adjuster has a complete picture. There's a difference, and it matters to your settlement.</p>
<h2>Step 3: File the Claim</h2>
<p>Once you've documented the damage and spoken with a contractor, file. Most Illinois homeowners have one year from the date of the storm to file a storm-related claim, but don't wait. Adjusters are backed up after major weather events, and the sooner you're in the queue, the sooner your project gets scheduled.</p>
<p>When you call to file, have these ready:</p>
<ul>
<li>The date and approximate time of the storm</li>
<li>Your policy number</li>
<li>The photos you took</li>
<li>A factual description of the damage (your contractor's inspection documents the specifics — keep your description general)</li>
</ul>
<h2>Step 4: The Adjuster Visit</h2>
<p>Your contractor should be on-site when the insurance adjuster arrives. This is non-negotiable. The adjuster's job is to assess damage; your contractor's job is to make sure nothing gets missed. A good contractor doesn't argue with the adjuster — they point to specific damage, explain how it affects the roof's performance, and back it up with documentation.</p>
<p>After the visit, the insurance company sends a claim summary listing what they will cover. Read it carefully. If your contractor's documented scope is larger than what the adjuster approved, you can file a supplement to have the additional items reviewed.</p>
<h2>Step 5: Understand How You Get Paid</h2>
<p>Most homeowner's insurance policies pay storm claims in two parts:</p>
<ol>
<li><strong>Actual Cash Value (ACV):</strong> The upfront payment, based on the depreciated value of the damaged materials. This arrives after the claim is approved.</li>
<li><strong>Recoverable Depreciation:</strong> The remaining balance, released by the insurance company after the work is completed and invoiced.</li>
</ol>
<p>You pay your deductible. The contractor is paid from the insurance proceeds. Do not sign with any contractor who offers to waive your deductible — that is insurance fraud under Illinois law, and it will void your claim.</p>
<h2>Step 6: Complete the Work and Close the Claim</h2>
<p>Once the roofing work is done, your contractor provides the insurance company with the final invoice and completion documentation. The carrier releases any withheld depreciation. The claim closes.</p>
<p>From the date of the storm to a closed claim, most residential roofing replacements in Chicagoland take four to eight weeks — depending on adjuster backlog and material lead times. Storms that affect a wide area take longer because every contractor and adjuster in the region is working at capacity.</p>
<h2>What Storm Restoration Experience Actually Means</h2>
<p>Not every roofing company handles insurance claims. Storm restoration requires understanding how adjusters scope damage, what documentation insurance carriers accept, and how to pursue a supplement when the initial scope is incomplete.</p>
<p>Culture Construction has handled hundreds of storm restoration projects across Chicagoland. We walk the roof with you before the adjuster arrives, and we're there when the claim closes. If you've had storm damage and aren't sure where to start, call us — the inspection is free and comes with no obligation to file a claim.</p>